AI Budget Planner vs. Traditional Spreadsheet: Which One Actually Gets Used?
Comparing AI budget planners and spreadsheets on the metric that matters most: sustained use. Find out which tool you'll actually stick with.
You made a budget. You even built the spreadsheet. And then, somewhere between setting it up and actually using it, life got busy and the whole thing quietly disappeared into a forgotten browser tab.
Sound familiar? You're not alone.
Here's the truth nobody tells you when you're comparing budgeting tools: the best one isn't the most powerful or the most feature-packed. It's the one you'll actually open next month. And the month after that.
This post breaks down the real difference between using an ai budget app and sticking with a traditional spreadsheet, but not in the way most comparisons do. Instead of listing features side by side, we're focusing on the thing that actually determines whether your budget works: whether you keep using it.
You'll learn why spreadsheets give you more control but cost you more time, how AI tools change the setup experience, and which option is genuinely the better fit depending on how much time you have to spare. By the end, you'll have a straight answer you can actually act on.
The Real Question Isn't Features, It's Whether You'll Open It Again
Most budget tool comparisons get this wrong from the start. They line up features, count integrations, and rank chart types, as if the tool with the longest list wins. But there's a more honest question to ask: which one will you still be opening six months from now?
That's the only metric that actually matters for your finances.
Research backs this up. Studies show 40% of technology spend underperforms not because tools lack functionality, but because people stop using them. The problem is almost never capability. It's adoption.
Think about the last time someone abandoned a spreadsheet budget. It wasn't because they needed pivot tables and didn't have them. It was because opening the file, finding the right tab, and manually entering two weeks of transactions felt like a chore they'd get to later. Later became never.
This is what researchers call the activation gap: the distance between signing up for a tool and actually getting recurring value from it. A tool can be free, powerful, and beautifully designed, and still fail completely if the gap between "I have it" and "I use it regularly" is too wide to cross on a busy Tuesday night.
It's a problem that goes deeper than most people realize, and it's the real reason so many budgeting attempts quietly disappear before spring.
This comparison isn't about features. It's about friction, maintenance, and the honest likelihood of repeated use. Everything else is secondary.
The Case for Spreadsheets: Control, Flexibility, and No Subscription
Let's be fair to spreadsheets before we make the case against them.
If you already live in Excel or Google Sheets, a budget spreadsheet costs you nothing and demands no new software to learn. You own the file. Nobody can change the pricing on you, sunset the platform, or lock your transaction history behind a paywall. That kind of data independence is genuinely valuable, and it is worth saying so plainly.
For users who are comfortable with formulas and actually enjoy building systems, spreadsheets can do things most AI tools cannot touch out of the box: rolling 12-month views, net worth dashboards, multi-category tracking with custom rules, and scenario modeling that reflects exactly how your finances work. Compared to those capabilities, statement-upload spend analysis tools look simpler, because for most users, simpler is the point.
The honest picture looks like this:
Full customization at zero recurring cost
No third-party dependency, so your data never relies on a company staying in business
No learning curve for anyone already fluent in spreadsheets
Real analytical depth for users who want to build beyond basic budgeting
For someone with existing skills and a consistent weekly routine, the maintenance overhead is manageable and the control payoff is real.
The spreadsheet is not the wrong tool for everyone. It is the wrong tool specifically for anyone who finds the setup process and ongoing upkeep a barrier to starting, or staying consistent. That distinction matters, and it is exactly where the comparison gets interesting.
The Spreadsheet Friction Problem: You Have to Build It Before You Can Use It
But those advantages only hold if you can get past the starting line.
Open a blank spreadsheet with the intention of building a budget and the first problem becomes immediately clear: there is nothing to use yet. Before you can record a single transaction, you have to decide on categories, build formulas, design a layout, and figure out how it all connects. That is system architecture work, not budgeting. The tool doesn't exist until you've built it.
This front-loaded cost is the primary reason spreadsheet budgets get abandoned early. The setup phase feels like a project you have to complete before the actual goal, understanding your spending, can even begin.
Research on workplace friction puts a number on this pattern. Employees lose 7.9 hours per week to friction, equivalent to 51 working days per year. Budget spreadsheets replicate this exact dynamic: every session spent building the system instead of using it is friction, not progress.
Critically, 47% of tool abandonment tied to friction comes from missing guidance rather than broken functionality. A blank spreadsheet has no prompts, no defaults, no suggested next step. That silence is the problem. There is nothing telling you what to do, so most people quietly close the tab.
There is also a useful benchmark worth knowing: if a core action cannot be completed within 90 seconds, adoption rates drop sharply. Finding the right tab, locating last week's entry, and adding new transactions rarely clears that bar. Choosing a bank statement converter that does more than hand you a raw CSV is one way to eliminate that exact bottleneck before it costs you the habit.
What an AI Budget Planner Actually Does Differently
So where does that leave the AI alternative?
An AI budget planner solves the spreadsheet problem at the source. Instead of asking you to build a system before you can use it, it does the setup work for you. You upload a file, and the tool returns a categorized picture of your spending. No formulas, no column headers, no decisions required before you can see anything useful.
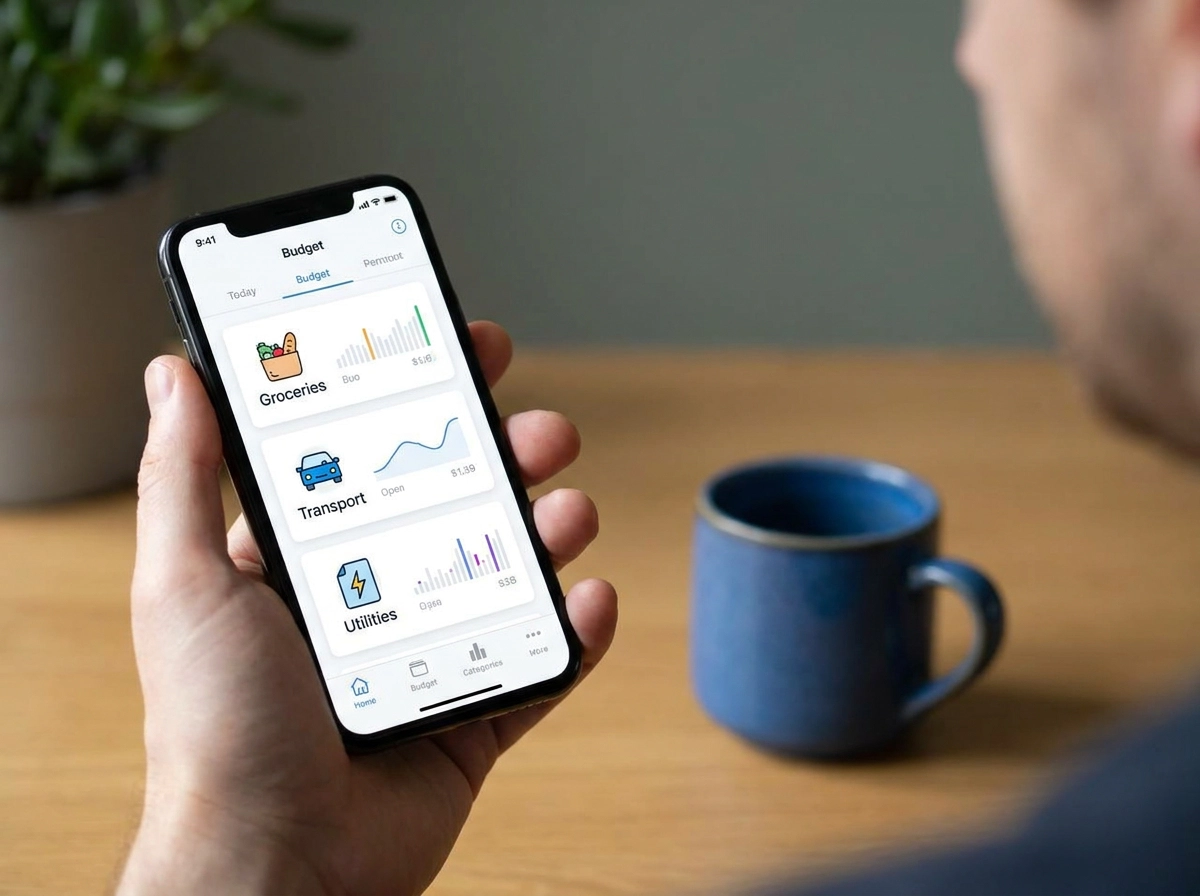
The mechanism that makes this work is automated bank statement parsing. Upload a PDF, CSV, XLS, or OFX file from your bank, and the AI extracts your transactions and sorts them into spending categories instantly. That single step eliminates manual data entry, which is the friction point that causes most spreadsheet budgets to stall in week two.
This also means you do not need any prior budgeting experience to get started. AI-driven categorization handles the financial literacy gap automatically. You do not need to know the "right" way to structure a budget because the structure already exists when you open it.
The result is a much smaller activation gap. With a spreadsheet, the job is to build something. With an AI budget planner, the job is to review something. That is a fundamentally easier ask, and it is why the probability of coming back next month is higher.
StatementToBudget.com puts this into practice with no cost attached. Upload a bank statement, receive AI-categorized spending insights immediately. No subscription, no trial period, no barrier between you and a working budget view.
When evaluating any ai budget app, ignore the chart count. The only question worth asking is: how fast does it show you your finances? Speed to first insight is what predicts whether you return.
The Hidden Cost Nobody Talks About: Ongoing Maintenance
Getting through setup is only half the battle. The part most ai budget planner comparisons skip entirely is what happens in month two, month three, and month six: the ongoing maintenance grind that quietly kills most budgets.
A spreadsheet budget doesn't maintain itself. Every week means manual transaction entry, checking that formulas didn't break, reconciling categories when your spending shifts, and occasionally rebuilding columns when your life changes. Each session might only cost 30 to 45 minutes, but that compounds fast. Over a year, a diligent spreadsheet budgeter spends roughly 25 to 35 hours just keeping the thing functional. That's before any actual financial thinking happens.
For a deeper look at what that process actually involves, Manual Reconciliation vs. Automated Tools: What Is the Difference? breaks down exactly where that time goes.
AI planners redistribute this burden rather than eliminate it. Automated categorization and transaction extraction handle the reconciliation work, so your job becomes reviewing results instead of rebuilding them. Upload a statement, scan the categories, flag anything odd. That's a 5 to 10 minute monthly task, not a weekly commitment.
That gap sounds modest until you apply it to real life. A 10-minute monthly review happens. A 30 to 45 minute weekly session gets skipped when work is hectic, when travel comes up, when anything comes up. And one skipped week becomes two, then the whole thing quietly stops.
This is where the best ai budgeting tool question becomes concrete rather than theoretical. Raw capability doesn't matter if the tool gets abandoned by March. A less powerful tool used consistently for six months will do more for your finances than a sophisticated one opened twice.
Which Tool Is Right for You: A Straight Answer by User Type
So which tool actually fits your life? Here is a direct answer by user type, no hedging.
Choose a spreadsheet if you already live in Excel or Google Sheets, you want to build something beyond basic budgeting (think net worth tracking or custom forecasting models), you are comfortable maintaining formulas, and you have a reliable weekly routine where you will genuinely sit down to update it.
Choose an AI budget planner if you have tried a spreadsheet before and abandoned it, your schedule is unpredictable, or you are starting completely from scratch. If you want budgeting to take minutes rather than sessions, the AI route is built for you.
The ChatGPT budget approach sits somewhere in the middle. Using a large language model to design or troubleshoot your spreadsheet does reduce the setup friction meaningfully, but it does not eliminate the ongoing manual entry requirement. You still have to do the weekly data work.
For most people searching for a budget planner online, the honest answer is straightforward: an AI planner wins on the dimension that matters most. You will still be using it in three months. A spreadsheet that requires 30 minutes of weekly upkeep gets dropped the first time life gets chaotic, and it always does eventually.
Neither tool is universally better. But if your primary obstacle is time and consistency rather than analytical depth, the lower-friction option is the better choice, full stop. If you are curious what a connected workflow looks like beyond the initial import, What to Do Next walks through exactly that.
Can You Use Both? The Hybrid Approach Worth Considering
If neither option feels like a perfect fit, you may not have to choose.
Some users get the best results from a hybrid workflow: let an AI tool handle the import, categorization, and initial analysis, then pull that structured data into a spreadsheet for deeper modeling or long-term tracking. You get the time savings at the data-entry stage without giving up the flexibility you already rely on.
This is particularly useful if you're transitioning away from spreadsheets but aren't ready to leave them behind entirely. Instead of manually typing in every transaction, you start with clean, categorized data that's ready to work with.
Why Statement to Budget?, StatementToBudget.com supports this workflow directly. Upload a bank statement in PDF, CSV, XLS, or OFX format, and the platform parses and categorizes your transactions instantly. The resulting structured data can feed into any downstream format you prefer, including your existing spreadsheet setup.
The hybrid model removes the part of spreadsheet budgeting that actually causes abandonment: manual entry. The analysis layer you've built stays intact. You just stop spending 30 minutes re-entering data before you can use it.
The same principle that runs through this entire comparison applies here too. The right combination isn't the most powerful one; it's the one that costs you the least time each week. A hybrid approach that eliminates data entry friction while keeping your preferred analysis tools is, for many users, the configuration they'll actually stick with.
The Bottom Line: Sophistication You Don't Use Is Worth Nothing
Whichever workflow you settle on, one principle holds across all of them: the best budget tool is the one with the lowest barrier to repeated use, not the one with the longest feature list.
The evidence points the same direction throughout this comparison. Friction drives abandonment more reliably than feature gaps do. Research suggests that nearly half of tool failures trace back to missing guidance rather than broken functionality, which maps exactly onto the blank-spreadsheet experience where there is no prompt, no default, and no next step. The 90-second accessibility benchmark matters because a tool that takes longer to navigate than your attention span will eventually stop getting opened.
If you have tried a spreadsheet and abandoned it, that is not a discipline problem. It is a maintenance overhead problem. The tool asked more of you than your schedule could reliably deliver, and eventually life got busy enough that it stopped happening.
For most people with a packed schedule, an AI budget planner that handles categorization and import automatically will produce more real financial improvement than a more powerful tool used twice a year. A working budget reviewed monthly beats a sophisticated model opened twice.
Before committing to any tool, it is also worth understanding what happens after you convert your statements. This practical guide to bank statement converters for personal budgeters covers exactly that.
The fastest way to test whether this approach works for you is to try it. Upload a recent bank statement to StatementToBudget.com and see a categorized budget view in under 90 seconds. That is the same threshold the research identifies as the tipping point for sustained adoption. If the tool earns that benchmark, you have your answer.
Conclusion
The right budgeting tool is not the most powerful one. It is the one you actually open next Tuesday.
Spreadsheets offer real flexibility and zero subscription costs, but they demand consistent time and maintenance most schedules cannot support. AI budget planners remove the setup barrier and automate the tedious work, making regular use genuinely realistic. And a budget reviewed monthly, even an imperfect one, will always outperform a sophisticated system gathering digital dust.
Three takeaways worth keeping: friction kills follow-through, automation earns consistency, and sophistication without usage is worthless.
If you have been on the fence, stop researching and start testing. Upload a single bank statement to StatementToBudget.com and have a categorized budget view in under 90 seconds. That one action will tell you more than any comparison article ever could. Your financial clarity is one upload away.