Budgeting Motivation Dies in Month Two. Here Is the Fix
Motivation is start-up fuel that runs out by month two. A ten-minute monthly statement review with one change each month keeps a budget alive.
Month one feels easy. You have a new budget, a fresh spreadsheet, and enough budgeting motivation to move mountains. Then month two arrives, and the spreadsheet gets quiet. You do not need more willpower. You need a feedback loop that keeps running when motivation does not.
At StatementToBudget, we treat this as an editorial position: budgets fail less from a lack of discipline than from a lack of feedback. In this tutorial, we will look at why budgets go quiet in month two, why motivation is start-up fuel rather than a system, and why the real failure point is usually feedback, not discipline. Then we will walk through a ten-minute monthly statement review. You will see how to run it step by step, apply the one-change rule, and make exactly one visible change per month. We will also cover what one change looks like in practice, how to keep the loop going without motivation, and where a statement to budget tool fits in. By the end, you will know how to run your first review this month and give your budget a better chance of surviving past the start.
Why Month Two Is Where Budgets Go Quiet
The pattern is predictable. A January budget or a 30-day budget challenge gets real attention for two or three weeks. Then tracking stops while spending quietly continues.
StatementToBudget's editorial position is that this drop-off is not a discipline failure. It is a feedback failure. A plan with no regular readout gives you nothing to react to.
The budget rarely dies loudly. You do not sit down and decide to quit. You just stop opening the spreadsheet, because nothing there surprised you, corrected you, or helped you decide anything. If you have already converted a statement, this budget-first workflow shows what to do with the data next.
Financial pressure on households has fluctuated noticeably over the past four years, a backdrop that makes personal tracking more, not less, important.
Motivation Is Start-Up Fuel, Not a System
Motivation is real, and it does one job well: starting. It gets you to open the account, download the template, or begin a money saving challenge in week one. Then the novelty runs out. A budget is deliberately the least novel thing you own, so by week five it has nothing new to offer.
Willpower is not a better bet. A 12-lab replication found only a tiny depletion effect, so building a plan on daily self-control rests on contested ground. Every unmade money decision draws on attention you could have spent once, in a monthly review that treats your bank statement as a feedback loop.
The costly misread is treating month one as proof the system works. It only proves the fuel worked. The budget was never read, so it was never tested.
So stop asking how to feel motivated again. Ask what your budget tells you back. That question has an answer. Motivation does not.
Why a Budget Challenge Stalls After the First Month
This is where a 30-day budget challenge or money saving challenge looks like the answer. The flaw is the finish line. It is built to end, and when it does, the structure leaves with it, along with the daily nudge.
Its design also rewards intensity over durability. No-spend weeks, extreme weekends, and rigid rules train habits sized for a sprint, not for a normal Tuesday in month two. In habit research, the median time to automaticity ran well past 30 days, so one month cannot build the routine by itself. Accountability fades on the same schedule: the group chat, shared tracker, or friend you reported to tends to go quiet exactly when your spending does not.
That does not make a challenge a waste. Run it once as a diagnostic. A tracked month hands you real numbers, and real spending you can actually see is the raw material a monthly review needs.
Then keep the artifact and drop the rules. Keep the logged spending, and swap the finish line for a ten-minute recurring review.
The Real Failure Point Is Feedback, Not Discipline
So the challenge fades, and the problem underneath isn't discipline. A budget answers a question once. You set the numbers before the month, and nothing during the month tells you whether they were realistic.
Without feedback, a bad plan and a bad month look identical. That ambiguity is why you blame yourself instead of adjusting one number. Feedback research points the same way: it changes performance, but not always for the better, and it works best when attention stays on the task.
A working loop does three things: shows what actually happened, compares it with what you expected, and produces one next action. Drop any of the three and it stops being useful. Behavior-change writing keeps returning to self-monitoring: people adjust when they see their own number. For money, visibility is a more actionable lever than willpower, that is the editorial argument here, not a research finding.
Honestly labeled: the month-two pattern and the review method below are StatementToBudget's editorial recommendations, not study findings. Test them against your last two months of statements. For tips anchored to real transaction patterns, see these budgeting tips that actually work for beginners.
The Ten-Minute Monthly Statement Review
So here is the whole method: once a month, same day, ten minutes, one statement, one change.
Its simplicity is why it survives a busy week. In our view, ten minutes is a deliberate ceiling, not an estimate. A review that takes an hour becomes an event you postpone, and a postponed review is the same as no review.
You need last month's bank statement in whatever format your bank gives you, plus a way to see spending grouped by category. A monthly statement review habit is what keeps categorizing from being the step you quietly skip.
Set a trigger tied to something already monthly: the day your statement closes, the first weekend, or the day after payday. Attach it to an existing event instead of a reminder you will dismiss.
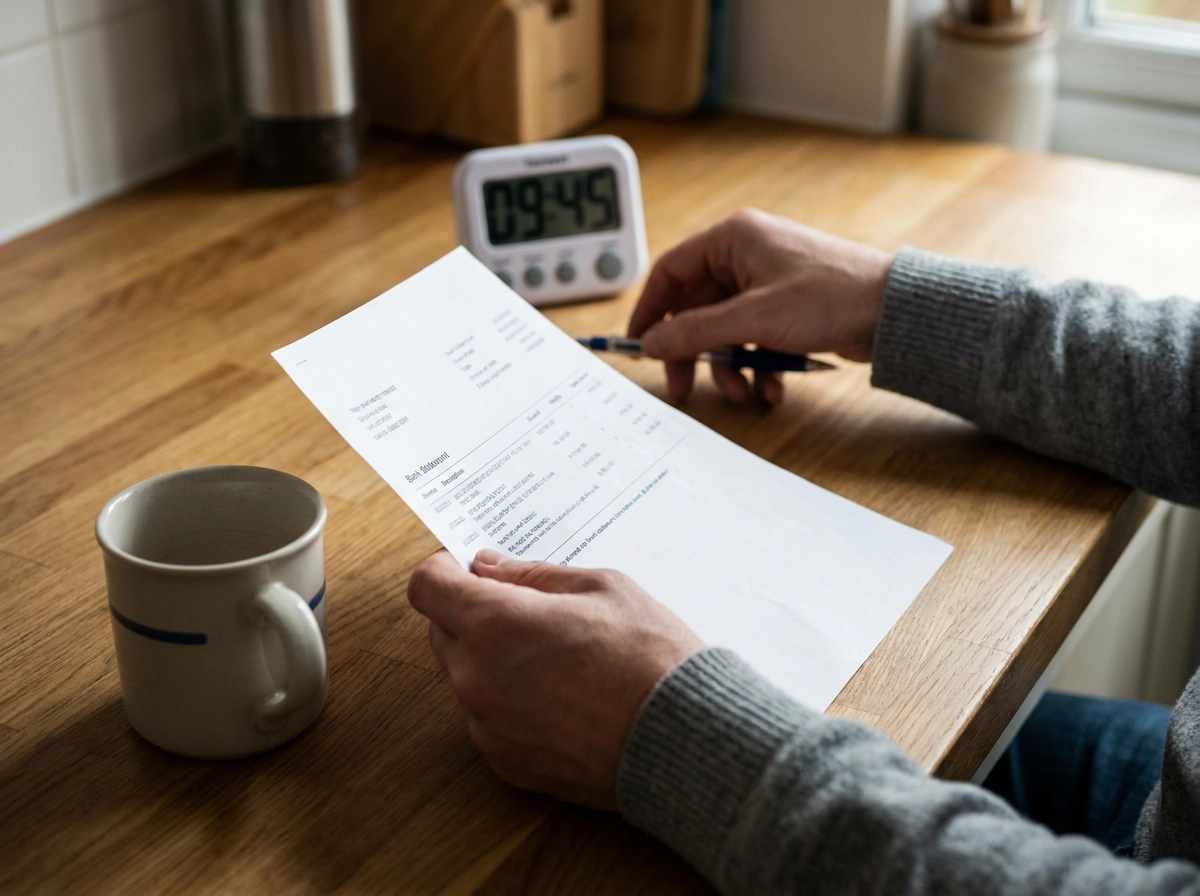
Keep a one-line log of every review: the date, what you noticed, what you changed. After three or four entries, that log becomes the memory your motivation never had.
Step by Step: How to Run It in Ten Minutes
Timer running. Minute 0 to 2: open the statement and scan for surprises. Duplicate charges, a subscription you forgot you had, a fee you did not expect. Circle them; no fixing yet.
Minutes 2 to 5: compare category totals against what you thought you spent. Look at your two or three largest categories only. Narrowing the scan keeps the review under ten minutes.
Minutes 5 to 8: find the single line that moved the most since last month, up or down, and decide whether that movement was intentional.
Minutes 8 to 10: write one change as a sentence containing a number, so next month can judge it objectively. Then close the file. Redesigning the whole budget now is how ten minutes becomes ninety and how the habit dies.
If categorizing by hand is what stalls you, start with this guide on building a personal budget from your bank statement before your first review.
The One-Change Rule: One Visible Change per Month
The sentence you just wrote only works if it is the only one. Exactly one change per review, and it needs a number in it. "Spend less on takeout" is a feeling. "Order takeout twice instead of four times" is a decision you can check next month.
One change is enforceable. A list of five is a wish, and the predictable outcome of a five-item list is zero completed items plus a quiet decision to stop the reviews altogether.
Choosing is easier than it sounds. Take the highest-dollar item, the easiest item, or the one you would still do on a genuinely bad week. Any of those three criteria works, as long as you pick only one.
There is also a no-change option. If the numbers look fine, the change can be to hold the line, which keeps the budgeting loop honest instead of manufacturing churn for its own sake.
Every change gets reviewed next month. That step converts a one-off decision into a habit and gives the loop its momentum.
What One Change Looks Like in Practice
The amounts below are illustrative starting points; choose figures that fit your own spending. Here are four from StatementToBudget's editorial method. Your numbers will differ.
Spending: Order delivery once a week instead of twice, then send the $60 difference to your credit card and check that balance next review.
Subscriptions: Cancel the streaming service you have not opened in 30 days. Write the monthly amount in your log, then confirm the charge is gone next month.
Income and saving: Set a $150 automatic transfer for the day after payday, so the money moves before the month can spend it.
Cash flow: Take $120 out in cash for groceries each week instead of using your card, then compare the grocery category at the next review.
Each is a recommendation, not a rule. The amount and item are yours to choose; picking one is the entire point. For the next step, see Once You Have Switched: Turning Your Statements Into a Budget.
Making the Loop Run Without Motivation
The change is the easy part. Coming back to check it is the loop, and the loop runs whether or not motivation shows up.
It has three parts: a fixed time, a visible number, a single action. None depends on how you feel that week.
Miss a month? Treat it as a scheduling problem, not a character flaw. Resume next month rather than restarting the budget from scratch, which throws away the data the loop needs. For the feedback side, see how to build better money habits using your bank statement as a feedback loop.
Track the loop, not the outcome. Most reviews completed in a year is a strong outcome, and completed reviews are the one measure fully in your control. After several reviews, patterns tend to surface on their own, and the review starts to feel worth doing. That is motivation arriving after the fact, not before.
Where a Statement to Budget Tool Fits In
The loop can run without motivation, but it still needs one input: categorized spending.
StatementToBudget converts uploaded bank statements in PDF, CSV, XLS, or OFX formats into categorized budget insights. Its stated features include AI-driven spending analysis, bank statement OCR, and transaction extraction, and the platform is offered at no cost. Free access matters for this method specifically, because a habit built on repetition cannot ride a one-time burst of effort or a paid commitment you abandon in month three.
Use it as the input step: upload the statement, read the categorized summary, then spend your ten minutes on the part that actually needs you, choosing the single change. Those capabilities are described by StatementToBudget itself. The tool shortens the setup. It does not replace the review, and the change is still a human decision.
Run Your First Review This Month
Now the loop needs a first turn, and that turn is yours. Pick a date in the next seven days, block ten minutes, and treat it as fixed. The date matters more than the intention.
When it arrives, scan your two or three largest categories only, no full rebuilds.
Write one change with a number, then schedule next month's review before you close this one. The second review is what proves the loop works; the first is only a test.
If categorizing by hand is the step you would skip, upload the statement to StatementToBudget first, and your ten minutes go to the one change instead.
Conclusion
The loop is simple: one monthly review, two or three categories, one change with a number.
Pick a date, upload your statement in PDF, CSV, XLS, or OFX, and make one change, the loop does the rest.