The Biggest Expense Category Is Not the Best Place to Cut
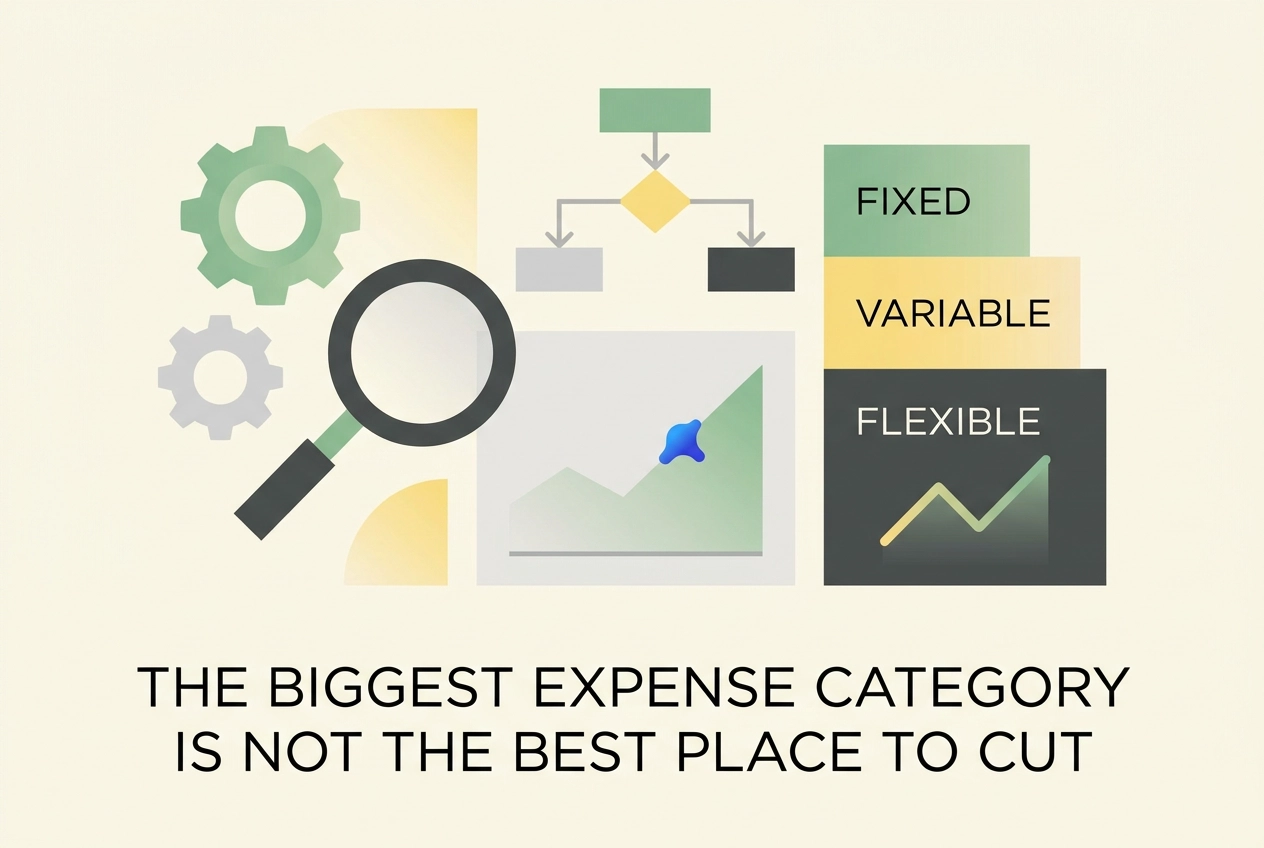
Rank your budget items by how changeable they are, not by size. Expense categorization shows why housing and transport rarely move, and what to cut first.
When money gets tight, the biggest line on your bank statement looks like the obvious place to cut. But housing, transportation, and insurance are usually the least flexible costs you have. That is why slashing the largest category often fails. The better first move starts with expense categorization: sorting your spending into clear groups before you rank anything.
In this beginner-friendly tutorial, we will look at why the biggest line on your statement is the hardest line to change, what expense categorization actually is, and how it decides your cut. You will see a budget items list you can rank, straight from the Consumer Expenditure taxonomy. Then we will explain why size is the wrong ranking criterion and walk through the three-question test: flexibility, frequency, and pain of change.
You will learn how to sort budget items into three tiers, from categories that move this month to those that barely move at all. We will cover where fixed and flexible really divide, work through a first move from statement to action, and show how to make that first move stick. Start with what moves, not with what is big.
Why the Biggest Line on Your Statement Is the Hardest Line to Change
Housing and transportation accounted for 50 percent of household spending in 2024, according to the Bureau of Labor Statistics, which is exactly why they are the two lines your eye lands on first. Cutting housing usually means moving, refinancing, or renegotiating a lease. Cutting transportation means selling a car, changing a commute, or re-shopping insurance mid-term.
The Texas A&M Real Estate Research Center finds spending shares are surprisingly stable decade to decade, with transportation falling and housing rising from 1984 to 2022. That stability is the problem: the biggest lines barely respond to one disciplined month, so the plan quietly collapses back to normal.
Reframe the job. Rank categories by how changeable they are, not how big, and a first action that actually sticks appears on its own. Before you rank, it pays to know where your money is actually going.
What Expense Categorization Actually Is, and Why It Decides Your Cut
A category is just a label that groups transactions by purpose. Housing swallows rent or mortgage, utilities, property tax, and household repairs under one heading.
That grouping decides what counts as a single line, which means it also decides what stays hidden. A subscription parked inside entertainment or miscellaneous stays invisible until you rename the label.
Fixed costs are locked by contract, lease, or necessity. Flexible costs vary month to month. The Consumer Expenditure Survey publishes more than 100 expense components spanning both kinds.
As a beginner, skip the question of which label is technically correct. Ask whether the label is narrow enough to act on. Once your statement is separated into real categories, what to do with your bank statement next becomes straightforward. You cannot rank or compare what you never split apart.
The Budget Items List You Can Rank, Straight From the Consumer Expenditure Taxonomy
That list exists. The Consumer Expenditure Survey publishes over 100 expense components, and its category list, released through FRED, works as a ready-made budget items list: housing, transportation, food, insurance and pensions, healthcare, entertainment, apparel, education, alcoholic beverages, personal care, reading, tobacco, and miscellaneous.
Housing plus transportation equaled 50 percent of 2024 household spending, anchoring the list. Those 50-percent-of-spending categories anchor the list; their 2024 growth rates (covered above) show how slowly the big lines move.
Use it as a template, then rename and merge items to match your statement's wording, since merchant names rarely map onto survey categories. Keep list and ranking separate: this is raw material; changeability is the sort you apply next.
Why Size Is the Wrong Ranking Criterion
Now that you have the list, resist ranking it by size. According to the Texas A&M Real Estate Research Center, housing is the largest Consumer Expenditure component, and mortgage holders spend the most on housing of any group. In Texas, lower-income households devote a higher share of income to housing than the national average, so the biggest line often has the least slack for the tightest budgets.
Transportation, the second-largest category, grew only 1.1% in 2024, the same 1.1% growth noted above. Large categories are frequently necessary, not waste, so the advice to look elsewhere applies mainly to your discretionary spending. The categories where households lose the most ground are rarely the easy cuts.
Ranking by size builds a plan around willpower, and the largest line is exactly where willpower moves least.
The Three-Question Test: Flexibility, Frequency, and Pain of Change
If size isn't the sort, what is? Try scoring each line 1 to 5 on three questions.
Flexibility: Can you change this month's amount without moving, selling a car, or breaking a contract?
Frequency: Does the charge repeat weekly, monthly, or annually? Frequent charges give feedback faster, so wins show up sooner.
Pain of change: What does changing cost in fees, time, or lifestyle? Cheap and reversible ranks above costly and permanent.
Add the three scores, then sort. High totals go first, low totals last.
Honest caveat: this is a practical screen, not a validated metric. It works like reading a bank statement for budget insights, not just balance checks: the individual lines carry the information.
Ranking Your Budget Items by Changeability
Now put those scores to work. Here is the shape of the ranking, with your numbers in the last column.
Category | Flexibility | Frequency | Pain of Change | Total |
|---|---|---|---|---|
Streaming | 5 | 4 | 5 | 14 |
Dining out | 4 | 5 | 3 | 12 |
Rent | 1 | 5 | 1 | 7 |
Scores are yours, not universal. A paid-off car and a fixed-rate lease rank differently from month-to-month rent. Expect most lines to cluster near the bottom; the few at the top are your first move. This is about where realistic change exists this month, not what you are allowed to spend. Rank lines you actually have, so build the list from your bank statement first.
Tier 1: The Categories That Move This Month
Your ranked table now has a top. These lines earn it.
Subscriptions and streaming skip contracts, cancel in a few clicks, and cost little to drop, so they are the first move for nearly everyone.
Food away from home repeats weekly with no contract, which means immediate savings. The pain is real if dining out is also your social life.
Apparel and entertainment are discretionary, plan-able, and easy to pause for a month without lasting consequences.
Personal care and reading carry small totals and trim simply by switching brands or formats. Treating your statement as a feedback loop shows whether the cut held.
One trap: if these lines already sit near zero, your ranking offers no first move, and the answer sits in Tier 2.
Tier 2: The Categories That Move With a Decision, Not a Snap
These categories move when you make a decision, not when you click cancel.
Groceries: weekly and contract-free, but the real ceiling is lower than it looks once staples are separated from treats and top-up trips.
Fuel and commuting: partly flexible. A route, a carpool, or a transit pass can change; the base commute usually cannot.
Phone and internet: changeable at renewal, with genuine switching pain and a penalty for leaving mid-term.
Utilities: the thermostat and the timing of heavy use can move; connection fees and the seasonal baseline cannot.
This tier holds the most durable savings, because you decide once instead of canceling repeatedly. Back each decision with budgeting tips that actually work for beginners so the change survives past month one.
Tier 3: The Categories That Barely Move at All
Housing is the largest category and the slowest to move. Moving, renegotiating a lease, or refinancing are projects with timelines, not budget edits.
Both insurance-and-pensions (up 2.5%) and transportation (up 1.1%) showed the low movement noted in the earlier data, amounts locked by policy term, loan schedule, or payroll deduction.
Childcare and healthcare are necessary costs with narrow substitutes, so they belong at the end of your ranking. Low-changeability does not mean untouchable. It means the change is a scheduled project, not a first move.
Where the Line Between Fixed and Flexible Really Falls
That tier list isn't an official system, though. No official taxonomy separates fixed from flexible in the way a personal budget needs. So draw it for your own life: a lease is fixed until renewal, a mortgage payment is fixed until refinance. Both turn flexible at a date you can name.
That's why the same category can land in different tiers for different households. It's also why blanket rules, like trimming every category by 20 percent, tend to fail. They ignore whether the money can actually move.
Dates are the bridge. A line that's fixed today but renegotiable in three months isn't an impossibility, it's a scheduled project.
The ranking earns its keep by telling you what to do this month while the fixed lines wait for their decision dates.
A Worked First Move: From Statement to One Action
Once you have named those dates, set them aside and work only from today's list.
Pull one month of your statement and group every transaction into the standard categories, leaving nothing in miscellaneous. Score each line, then read the top of the list. Check totals, not headlines: a small subscription that actually disappears beats a theoretical larger saving from a lease you cannot break this month.
Choose one action and attach a date and a number to it. Canceling two services on the same day for a known monthly reduction is a concrete first move. Verify it in your next statement, and keep your labels consistent so month-to-month comparison still holds.
Then work down the middle tier, and put the fixed lines on a calendar for their next renewal, refinance, or loan-end window.
Get Your Own Categorized List Before You Rank Anything
That worked first move depends on one thing: a categorized list. A raw statement is where most ranking attempts die. Merchant names and dates form a wall, not a list, so nothing ever gets scored.
StatementToBudget is a free tool that accepts a bank statement in PDF, CSV, XLS, or OFX format and uses bank statement OCR and transaction extraction to convert it into categorized budget insights with AI-driven spending analysis. That output is the grouped list this method needs: standard categories first, then your own flexibility, frequency, and pain-of-change scores layered on top.
It will not rank or score categories for you. That judgment stays with you, which is the point.
One statement is enough for a first pass; the tool is free, so there's no reason to put off categorizing.
How to Make the First Move Stick
Once your list exists, pick one action. Not five. The ranking's whole value is that a single changeable line carries the plan further than a broad, painful one.
Bind that action to a trigger you already have: a payday, a renewal notice, or the day you review your statement. Then track the category, not the outcome. A falling line in a consistently labeled category is visible evidence, though treat the habit-building advice here as reasoned guidance rather than settled research.
Re-rank quarterly. Categories shift tiers as leases end, loans close, and policies renew. Big categories will stay put in the short run. That is a schedule, not a failure. Work down the middle tier while the fixed lines wait for their dates.
Conclusion: Start With What Moves, Not With What's Big
Once your first move holds, reuse the logic: rank spending by changeability, not size. Use the Consumer Expenditure categories as your budget items list. Start at the top of your own ranking with one action, one number, and one date, and let expense categorization do the rest. Keep the fixed categories on a calendar for renewal windows instead of forcing them into a monthly plan they were never going to survive. Get a categorized list from a real statement first, so the ranking reflects what you actually spend, not what you remember spending. Small and movable beats big and stuck.